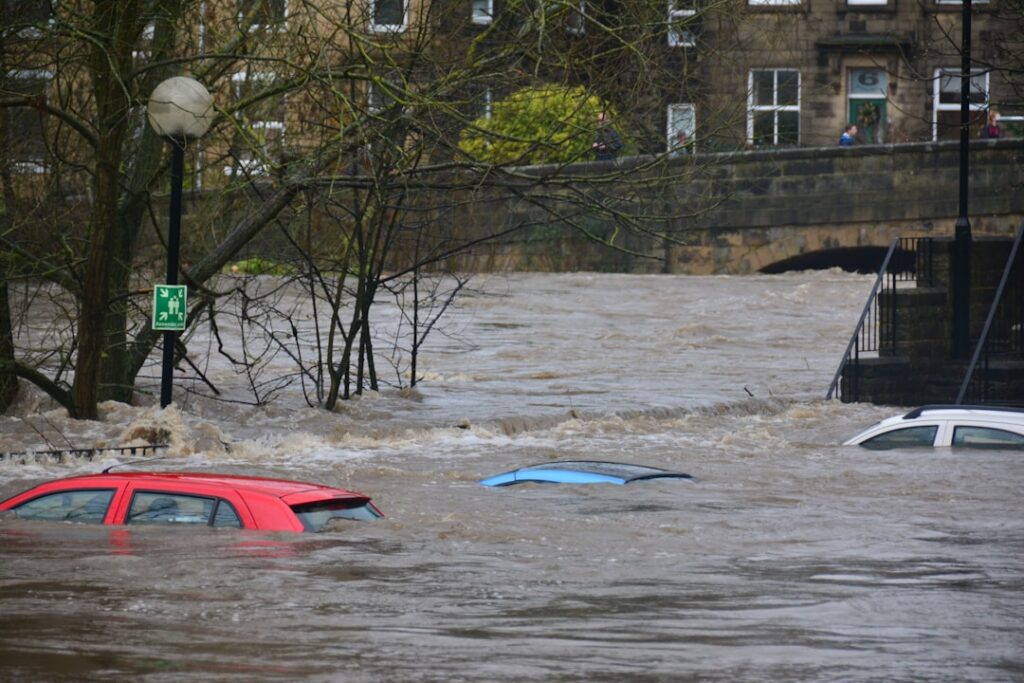
Plenty of homeowners assume their policy will handle anything wet, and then a heavy storm fills the basement and the claim is denied. Is flood damage covered by homeowners insurance? In most standard policies, no. Flood, surface water and water that seeps up through the ground are typically excluded. Flood coverage is usually bought as a separate policy, and water that backs up through drains generally requires its own endorsement.
That said, not every rain-related loss counts as a flood. Rain that enters through a roof damaged by wind, for example, is treated very differently from water rising in a basement. Policies vary by insurer, state and form, so read your own policy and ask your agent or insurer exactly which water scenarios are covered. This is general guidance, not legal or financial advice.
- Is Flood Damage Covered by Homeowners Insurance? Why It Is Usually Excluded
- How Separate Flood Policies Fit In
- Sewer and Water Backup Endorsements
- Rain Scenarios: What Is Typically Covered and What Is Not
- What to Do After Water Enters Your Home
- Questions to Ask Your Agent Before the Next Storm
- Flood Insurance and Finished Basements
- Reducing Flood and Backup Risk
- Cost Ranges and When to Call a Pro
- Frequently Asked Questions
Is Flood Damage Covered by Homeowners Insurance? Why It Is Usually Excluded
Insurers spread risk across many homes. Flooding breaks that model because a single storm can damage thousands of houses in the same area at the same time. For that reason, standard homeowners forms generally exclude:
- Flood, meaning overflow of rivers, lakes, streams or coastal storm surge.
- Surface water, such as heavy rain pooling across a yard and flowing into a basement door or window well.
- Water below the surface of the ground, including groundwater pushing through foundation walls or slab cracks.
- Mudflow and related movement of saturated soil.
Some people still believe flood damage is normally covered in a homeowner’s insurance policy. It is one of the most common misconceptions in home coverage, and it tends to surface after a storm when the gap is most painful.
How Separate Flood Policies Fit In
Flood insurance is generally sold as its own policy, through a federal program or private insurers, often arranged by the same agent who handles your homeowners coverage. Key points to understand:
- Two parts: building coverage for the structure and its systems, and contents coverage for belongings. They are often purchased and priced separately.
- Waiting period: new flood policies commonly have a waiting period before coverage starts, often around 30 days, with some exceptions. Buying coverage when a storm is already forecast is usually too late.
- Basement limits: flood policies often restrict what is covered in basements, typically focusing on essential equipment such as furnaces, water heaters and electrical panels, while excluding finished walls, flooring and many stored items.
- Not just high-risk zones: a meaningful share of flood claims come from homes outside mapped high-risk areas.
If your mortgage lender requires flood coverage, you already have a policy. If not, ask your agent for a quote and for a plain explanation of what it would and would not cover in your home.
Sewer and Water Backup Endorsements
Water coming up through floor drains, toilets or tubs because a sewer line or drain is overloaded is a different risk. Standard homeowners policies usually exclude it. A water backup endorsement, added to your homeowners policy for an extra premium, typically covers this scenario up to its own limit.
Many backup endorsements also address sump pump failure or overflow. If your basement depends on a sump pump to stay dry, this endorsement deserves serious attention. Limits vary widely, from a few thousand dollars to much higher, and the cost of a finished basement cleanup can easily exceed a low limit.
Rain Scenarios: What Is Typically Covered and What Is Not
Rain causes damage in several ways, and the route the water takes usually decides coverage.
Rain through a storm-damaged roof or wall
If wind, hail or a falling tree opens the roof and rain pours in, the resulting interior damage is commonly covered under many policies, because the storm caused a sudden opening. Prompt temporary repairs such as tarping are usually expected.
Rain through an old, worn roof
Leaks through aging shingles or failed flashing without a storm event are often treated as maintenance and excluded.
Rain pooling and entering the basement
Does insurance cover basement flooding from rain that runs across the yard and enters through a window well or door? Usually not under the homeowners policy, since it is surface water. A flood policy may apply, within its basement limits.
Groundwater through foundation walls
Water seeping through block walls or slab cracks after days of rain is generally excluded from homeowners coverage as water below the surface.
Rain overwhelming the sump pump or sewer
Does homeowners insurance cover flooding from rain that backs up through drains or overwhelms the sump? Typically only if you carry a water backup endorsement.
What to Do After Water Enters Your Home
- Put safety first. Do not walk into a flooded basement if water may be in contact with outlets, appliances or the electrical panel. Have the utility or a licensed electrician shut off power if you cannot reach the breaker from a dry area.
- Avoid contaminated water. Floodwater and sewer backup can carry bacteria and chemicals. Wear rubber boots, gloves and eye protection.
- Document the scene with photos and video before cleanup, including water depth against a wall with a tape measure.
- Report to every relevant insurer. If you have both homeowners and flood policies, notify both, since different parts of the loss may fall under each.
- Begin drying. Pump out standing water, remove soaked carpet and pad, and run fans and dehumidifiers. Keep samples of damaged materials if your insurer requests them.
- Save receipts for pumps, fans, cleanup supplies and temporary housing.
Wet materials can grow mold within 24 to 48 hours, so drying quickly protects both your health and your claim.
Questions to Ask Your Agent Before the Next Storm
A short conversation with your agent is the fastest way to find gaps. Bring your declarations page and ask these questions directly:
- Does my policy exclude flood, surface water and groundwater, and how does it define each?
- Do I have a water backup endorsement, and what is its limit and deductible?
- Does the backup coverage include sump pump failure, overflow or power outages that stop the pump?
- Is my home in a mapped flood zone, and what would a flood policy cost for building and contents?
- What would a flood policy cover in my basement specifically?
- Is rain entering through storm damage to the roof or windows covered, and what temporary repairs do you expect me to make?
- How would a claim affect my premium or renewal?
Write down the answers and ask the agent to confirm key points by email. Review them each year at renewal, especially after finishing a basement or adding valuable equipment downstairs, since those changes raise the stakes of a water loss.
Flood Insurance and Finished Basements
Finished basements deserve extra attention because they combine the highest water risk with the most limited coverage. Carpet, drywall, paneling and furniture on a basement level are often outside flood policy basement coverage, and they are usually excluded from homeowners policies when the source is surface water or groundwater. A water backup endorsement can help when water comes through drains, but only up to its limit. If you are planning to finish a basement, choose water-tolerant materials such as tile, luxury vinyl and moisture-resistant wall panels, and keep valuables elevated.
Reducing Flood and Backup Risk
Insurance pays after a loss. These steps help keep water out in the first place:
- Extend downspouts 4 to 6 feet or more from the foundation and keep gutters clear.
- Grade soil so it slopes away from the house.
- Install window well covers and keep wells free of debris.
- Test the sump pump each season by pouring water into the pit, and consider a battery backup pump.
- Ask a plumber about a backwater valve on the main sewer line if backups are a local problem.
- Raise the furnace, water heater and washer on platforms in flood-prone basements.
- Store valuables and documents off the basement floor in sealed bins.
Cost Ranges and When to Call a Pro
Basement water cleanup ranges from a few hundred dollars for minor drying to many thousands for removing finished walls, flooring and insulation. Flood insurance premiums vary greatly by location, elevation and coverage amount. Water backup endorsements are commonly modest in annual cost relative to the potential loss.
Call a water restoration company for large or contaminated water losses, a licensed electrician before restoring power to flooded areas, and a licensed plumber for sump pump installation, backwater valves and sewer issues. For repeated basement water, a foundation or drainage contractor can evaluate grading, drain tile and waterproofing options.
Frequently Asked Questions
Does homeowners insurance cover flooding from rain?
Usually not when rain pools as surface water or seeps through the ground. Rain entering through a sudden storm-caused opening in the roof or walls is more often covered.
How do I get flood coverage?
Flood insurance is generally a separate policy, available through a federal program or private insurers. Ask your agent for a quote and details on waiting periods.
Is sump pump failure covered?
Often only if you add a water backup endorsement, which usually has its own limit. Check your policy wording.
Does flood insurance cover a finished basement?
Flood policies commonly limit basement coverage to essential equipment and exclude finished walls, floors and many contents. Review the basement section carefully.
Should I report water damage to both insurers?
If you have homeowners and flood policies, notify both. Each may cover different parts of the loss.