Wind doesn’t damage a roof the way hail does. Hail bruises; wind pries. Gusts create uplift at edges, rakes, and ridges, lifting shingle tabs until adhesive seals break, shingles crease along the nail line, or whole tabs tear away. The tricky part of wind damage roof repair is that the worst damage is often nearly invisible from the ground — a creased shingle lies back down and looks fine until the next storm finishes it, or until water finds the broken seal. This guide walks the full sequence: what wind actually does to a roof, how to assess and document it, emergency measures, the insurance claim process, and what repairs cost.
Part of our Roofing guide — explore the full guide →
How Wind Damages a Roof
Wind loads aren’t uniform across a roof. Uplift concentrates at perimeters and corners — pressures at eaves, rakes, and ridge corners can run two to three times the field pressure. That’s why wind damage almost always starts at edges and works inward. The damage hierarchy, roughly in order of wind speed:
- Broken seal strips (45–60 mph). Tabs lift and lie back down. Invisible from the ground, but the shingle is now unsealed and will flap, crease, or blow off in the next event.
- Creased shingles (55–70 mph). The tab folds back over the nail line and hinges. The crease fractures the mat — a creased shingle is functionally dead even though it may look intact. Look for a faint horizontal line of granule loss across tabs.
- Torn or missing shingles/tabs (60–90 mph). Obvious from the ground: exposed black underlayment or bare deck, shingle pieces in the yard.
- Lifted flashing, ridge caps, and edge metal (varies). Ridge caps take the highest suction on the roof and are usually the first complete losses.
- Wind-driven debris impact. Branch strikes puncture; falling limbs crush decking.
Note that damage patterns differ by material. Asphalt shingles crease and tear; metal panels show lifted eave edges and backed-out fasteners; on a cedar shake roof, wind splits and slides shakes rather than creasing them.
Assessment Checklist: After the Storm
Do the ground survey first — most of this checklist needs no ladder:
- Yard and gutters: shingle tabs, ridge cap pieces, or heavy granule piles at downspout outlets.
- Roof edges through binoculars: lifted or wavy eave lines, missing drip edge, curled starter course.
- Field scan by slope: work slope by slope looking for color-flash (exposed underlayment), horizontal crease shadows, and shingles sitting proud.
- Ridge and hips: missing or cracked caps.
- Penetrations: tilted pipe boots, displaced chimney flashing, spun vents.
- Soffit, fascia, and gutters: wind that damaged the roof frequently peels these too — and they’re claimable.
- Attic inspection with a flashlight: daylight through the deck, wet sheathing, damp insulation directly below suspect areas.
- Interior ceilings: new stains, especially along exterior walls (edge damage shows up here first).
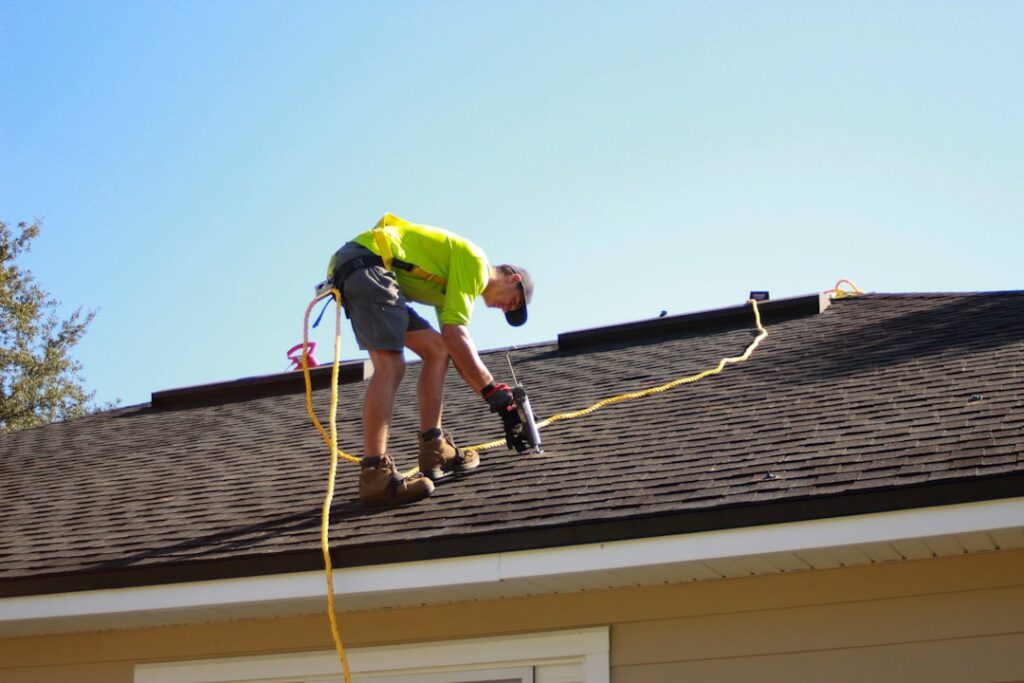
On the roof itself — only if the pitch and your footing allow — gently lift tab edges along eaves and rakes. Unsealed tabs lift with no resistance; sealed tabs fight back. Mark every crease and unsealed run with chalk and photograph everything: wide shots establishing the slope, mid shots showing the pattern, close-ups with a tape measure for scale. Date-stamped photos are the backbone of your claim.
Emergency Measures: Stop the Water First
Insurers require you to mitigate further damage, and they reimburse reasonable emergency costs — keep every receipt. If shingles are missing or the deck is breached and rain is coming:
- Tarp the breach. A properly installed tarp — carried over the ridge, battened with furring strips, never nailed flat through the field — will hold for weeks. Our roof tarp guide covers the full anchoring method and sizing.
- Move water indoors. Puncture sagging ceiling bubbles over a bucket (yes, really — a controlled drain beats a collapsed ceiling), pull wet insulation, run fans.
- Don’t make permanent repairs yet. Temporary mitigation is required; permanent repairs before the adjuster documents the damage can complicate the claim.
The Insurance Claim, Step by Step
- Review your policy. Note your wind/hail deductible (often a separate 1–2% of dwelling coverage deductible, not your flat one — on a $400,000 dwelling, a 1% wind deductible is $4,000), and whether you have replacement cost (RCV) or actual cash value (ACV) coverage.
- Document before anything is touched. Photos, video, the date of the storm, and a weather report or NWS local storm report confirming wind speeds that day.
- Get a contractor’s inspection first. A reputable local roofer will document damage in adjuster-friendly terms and tell you honestly whether the damage clears your deductible. If it’s a $900 repair against a $4,000 deductible, skip the claim — claims history affects premiums.
- File promptly. Most policies require “prompt” notice; many states allow one year or more for wind claims, but evidence degrades and deadlines vary. File within days, not months.
- Attend the adjuster inspection — with your roofer. This is the single highest-leverage move. Your contractor walks the roof with the adjuster, points out every crease and broken seal, and argues scope on the spot.
- Push on matching and slope-replacement rules. If your shingle is discontinued, many states and policies require replacing the full slope (or roof) so repairs match reasonably. Creased-but-attached shingles are damaged shingles — insist they’re in scope, not just the missing ones.
- Review the estimate line by line. Check for underlayment, drip edge, starter, ridge caps, flashing, disposal, and steep/height charges. Supplements for missed items are normal — your roofer files them.
- Understand the payment flow. With RCV coverage you typically get an ACV check up front, then the recoverable depreciation after the work is complete and invoiced.
If the claim is denied or lowballed and your contractor’s documentation is solid, ask for a re-inspection, then escalate to a licensed public adjuster (they take 10–15% but often move stuck claims) or invoke the policy’s appraisal clause.
Repair Costs Without (or Below) Insurance
| Repair | Typical cost |
|---|---|
| Replace 10–20 blown shingles | $250–$750 |
| Re-seal lifted tabs (hand-seal with adhesive) | $150–$400 |
| Ridge cap replacement (per 20 lf) | $200–$500 |
| Pipe boot or vent replacement | $150–$350 |
| Flashing rework at chimney/wall | $300–$900 |
| Full slope replacement | $1,500–$4,500 |
| Full roof replacement (asphalt, average home) | $9,000–$18,000 |
Spot repairs on a roof under 12–15 years old are usually worthwhile. On an older roof, widespread broken seals mean the whole field is one storm from failure — put repair money toward replacement instead. For the general diagnostics and patching techniques that apply beyond wind events, see our roof repair guide.
Mistakes That Sink Wind Claims
- Waiting months to file. Adjusters attribute aged, weathered damage to wear and tear, which isn’t covered.
- Letting a storm-chaser sign you before the adjuster visit. Door-knockers following storms range from fine to fraudulent. Never sign an assignment of benefits on the doorstep; use an established local contractor.
- Reporting only missing shingles. Creases and broken seals are the bulk of real wind damage — an inspection that only counts bare spots undercounts the loss badly.
- Making permanent repairs before documentation. Tarp and photograph; don’t re-shingle.
- Skipping the attic. Interior evidence of water intrusion strengthens scope and proves the damage is functional, not cosmetic.
- Filing a claim under the deductible. A claim on your record with zero payout is the worst of both worlds.
FAQ
What wind speed damages a roof?
Standard three-tab shingles are rated to 60 mph and start sustaining seal and crease damage in 45–60 mph gusts, especially when aged. Architectural shingles rated 110–130 mph resist far more, but edge and ridge damage still occurs in strong thunderstorm gusts.
Will insurance pay for a whole new roof from wind damage?
If damage is distributed across multiple slopes, or your shingle is discontinued and your state has matching requirements, full replacement is a common outcome. Localized damage on one slope typically gets a repair or single-slope scope.
Is a lifted shingle that lies back down really damaged?
Yes. The factory seal is broken and won’t fully rebond, and the mat may be creased. It will fail in a future event — which insurers may then call “old damage.” Document and claim it now.
How long do I have to file a wind claim?
Policy language governs — commonly “prompt notice” with suit limitation periods of one to two years. Practically: file within a week of discovery.